
Apple Introduces ‘Buy Now, Pay Later’ Plan For More Flexibility In Purchases
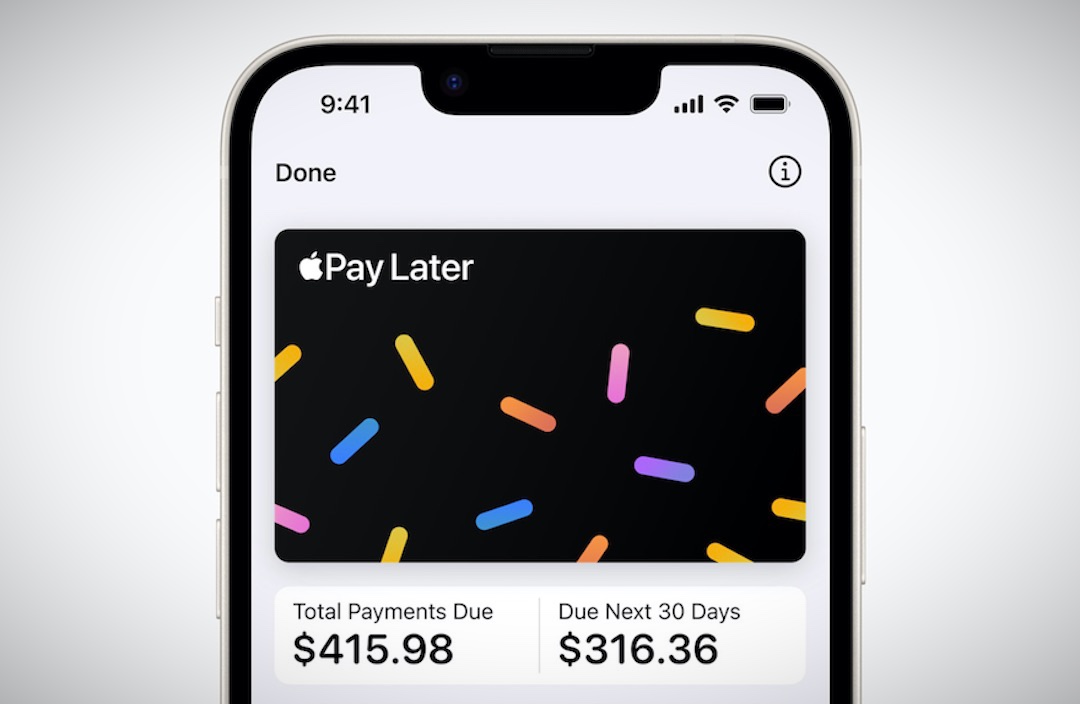
Apple is steadily releasing its new ‘Pay Later’ feature, which allows users to buy goods in four separate payments.
Apple Pay has become one of customers’ and retailers’ most used purchasing methods. Reuters points out that more than 85% of stores in the US utilize this form of transaction. The ease of having all your cards stored in your phone has pretty much rendered carrying physical cards useless. Not to mention that the pandemic spurred on a new contactless payment wave, which saw the use of hard cash dwindle even further.
With Apple’s new feature, users can get loans between $50 and $1,000 when purchasing online or in-app without interest or fees. Customers will then make the next payments over six weeks.
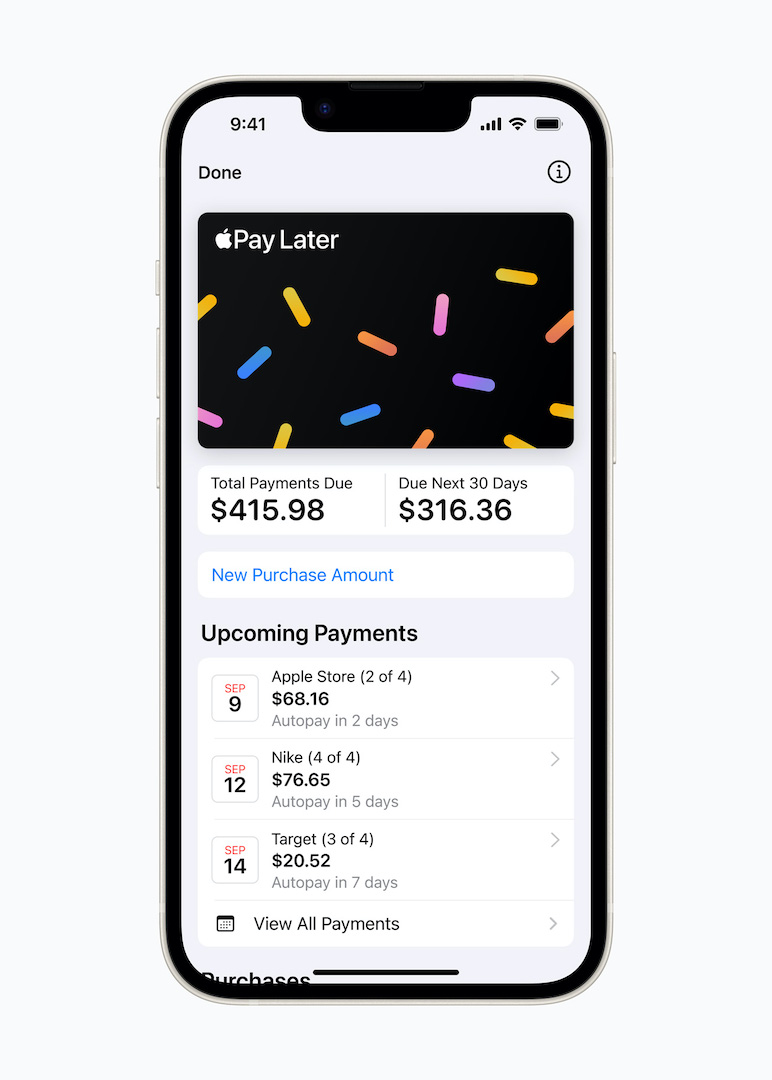
CNN points out that while this may allow people to stretch out their finances, consumer advocates posit that this could also cause more customers to incur debt as more of the public shifts to taking loans while shopping in an era of economic downturn.
“There’s no one-size-fits-all approach when it comes to how people manage their finances,” commented Apple’s vice president of Apple Pay and Apple Wallet, Jennifer Bailey. “Many people are looking for flexible payment options, which is why we’re excited to provide our users with Apple Pay Later.”
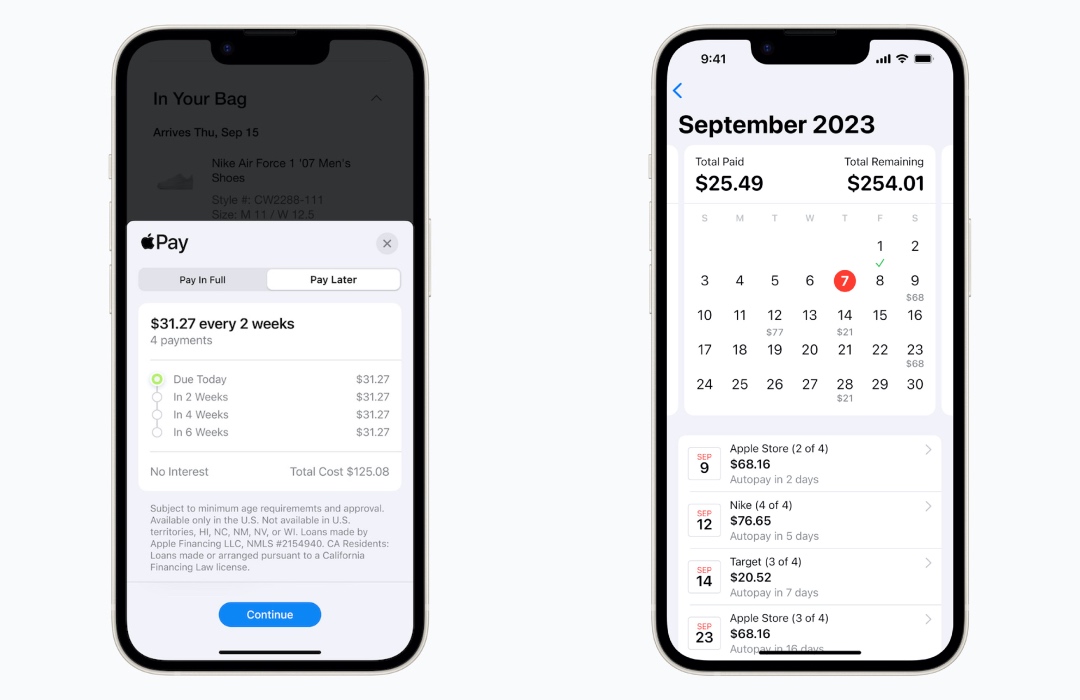
Pay Later is built into the Wallet and will update users on their progress. It can even connect to the Calendar app for a quick schedule overview.
The venture is enabled through a partnership with the Mastercard Installments program and Goldman Sachs as the issuer of the payment credential.
The feature has currently been rolled out to select users in the US.


